

For UHNI and HNI investors
No profit share.
Shares in your name.
The systematic equity a PMS or AIF sells, without 2% a year plus 20% of the gains: institutional grade index algos in your own demat, for one fee per rebalance.
- PMS, typical
- 2% + 20%
- ₹50 lakh minimum
- AIF Cat III, typical
- ~2% + 20%
- ₹1 crore minimum
- RupeeCase
- 0.2%
- of traded value, per rebalance
01Fee drag
What 2% plus 20%
costs, in rupees.
The same return before costs for all three. The only difference between the bars is the fee. Slide the amount.
₹79.0 lakhmore left with RupeeCase than with a PMS at 2% plus 20%, after 10 years at 12% a year before costs.
Left after feesLost to fees, against no fees
Lost to fees, compoundedRupeeCase PMS
Illustration, not a forecast: one return before costs for every option, minus each option's typical fee, compounded, as on the RupeeCase vs pages. Brokerage and taxes left out for all. PMS and AIF fees vary by manager; minimums are the SEBI floors. Not a recommendation to invest any amount.
02Side by side
Three ways to own
systematic equity.
RupeeCase minimums from the published lineup of 17 Jul 2026; they move with the prices of the holdings. PMS and AIF: typical terms and SEBI minimums; each product's own documents govern.
03Before you commit
Compare. Validate.
Then invest.
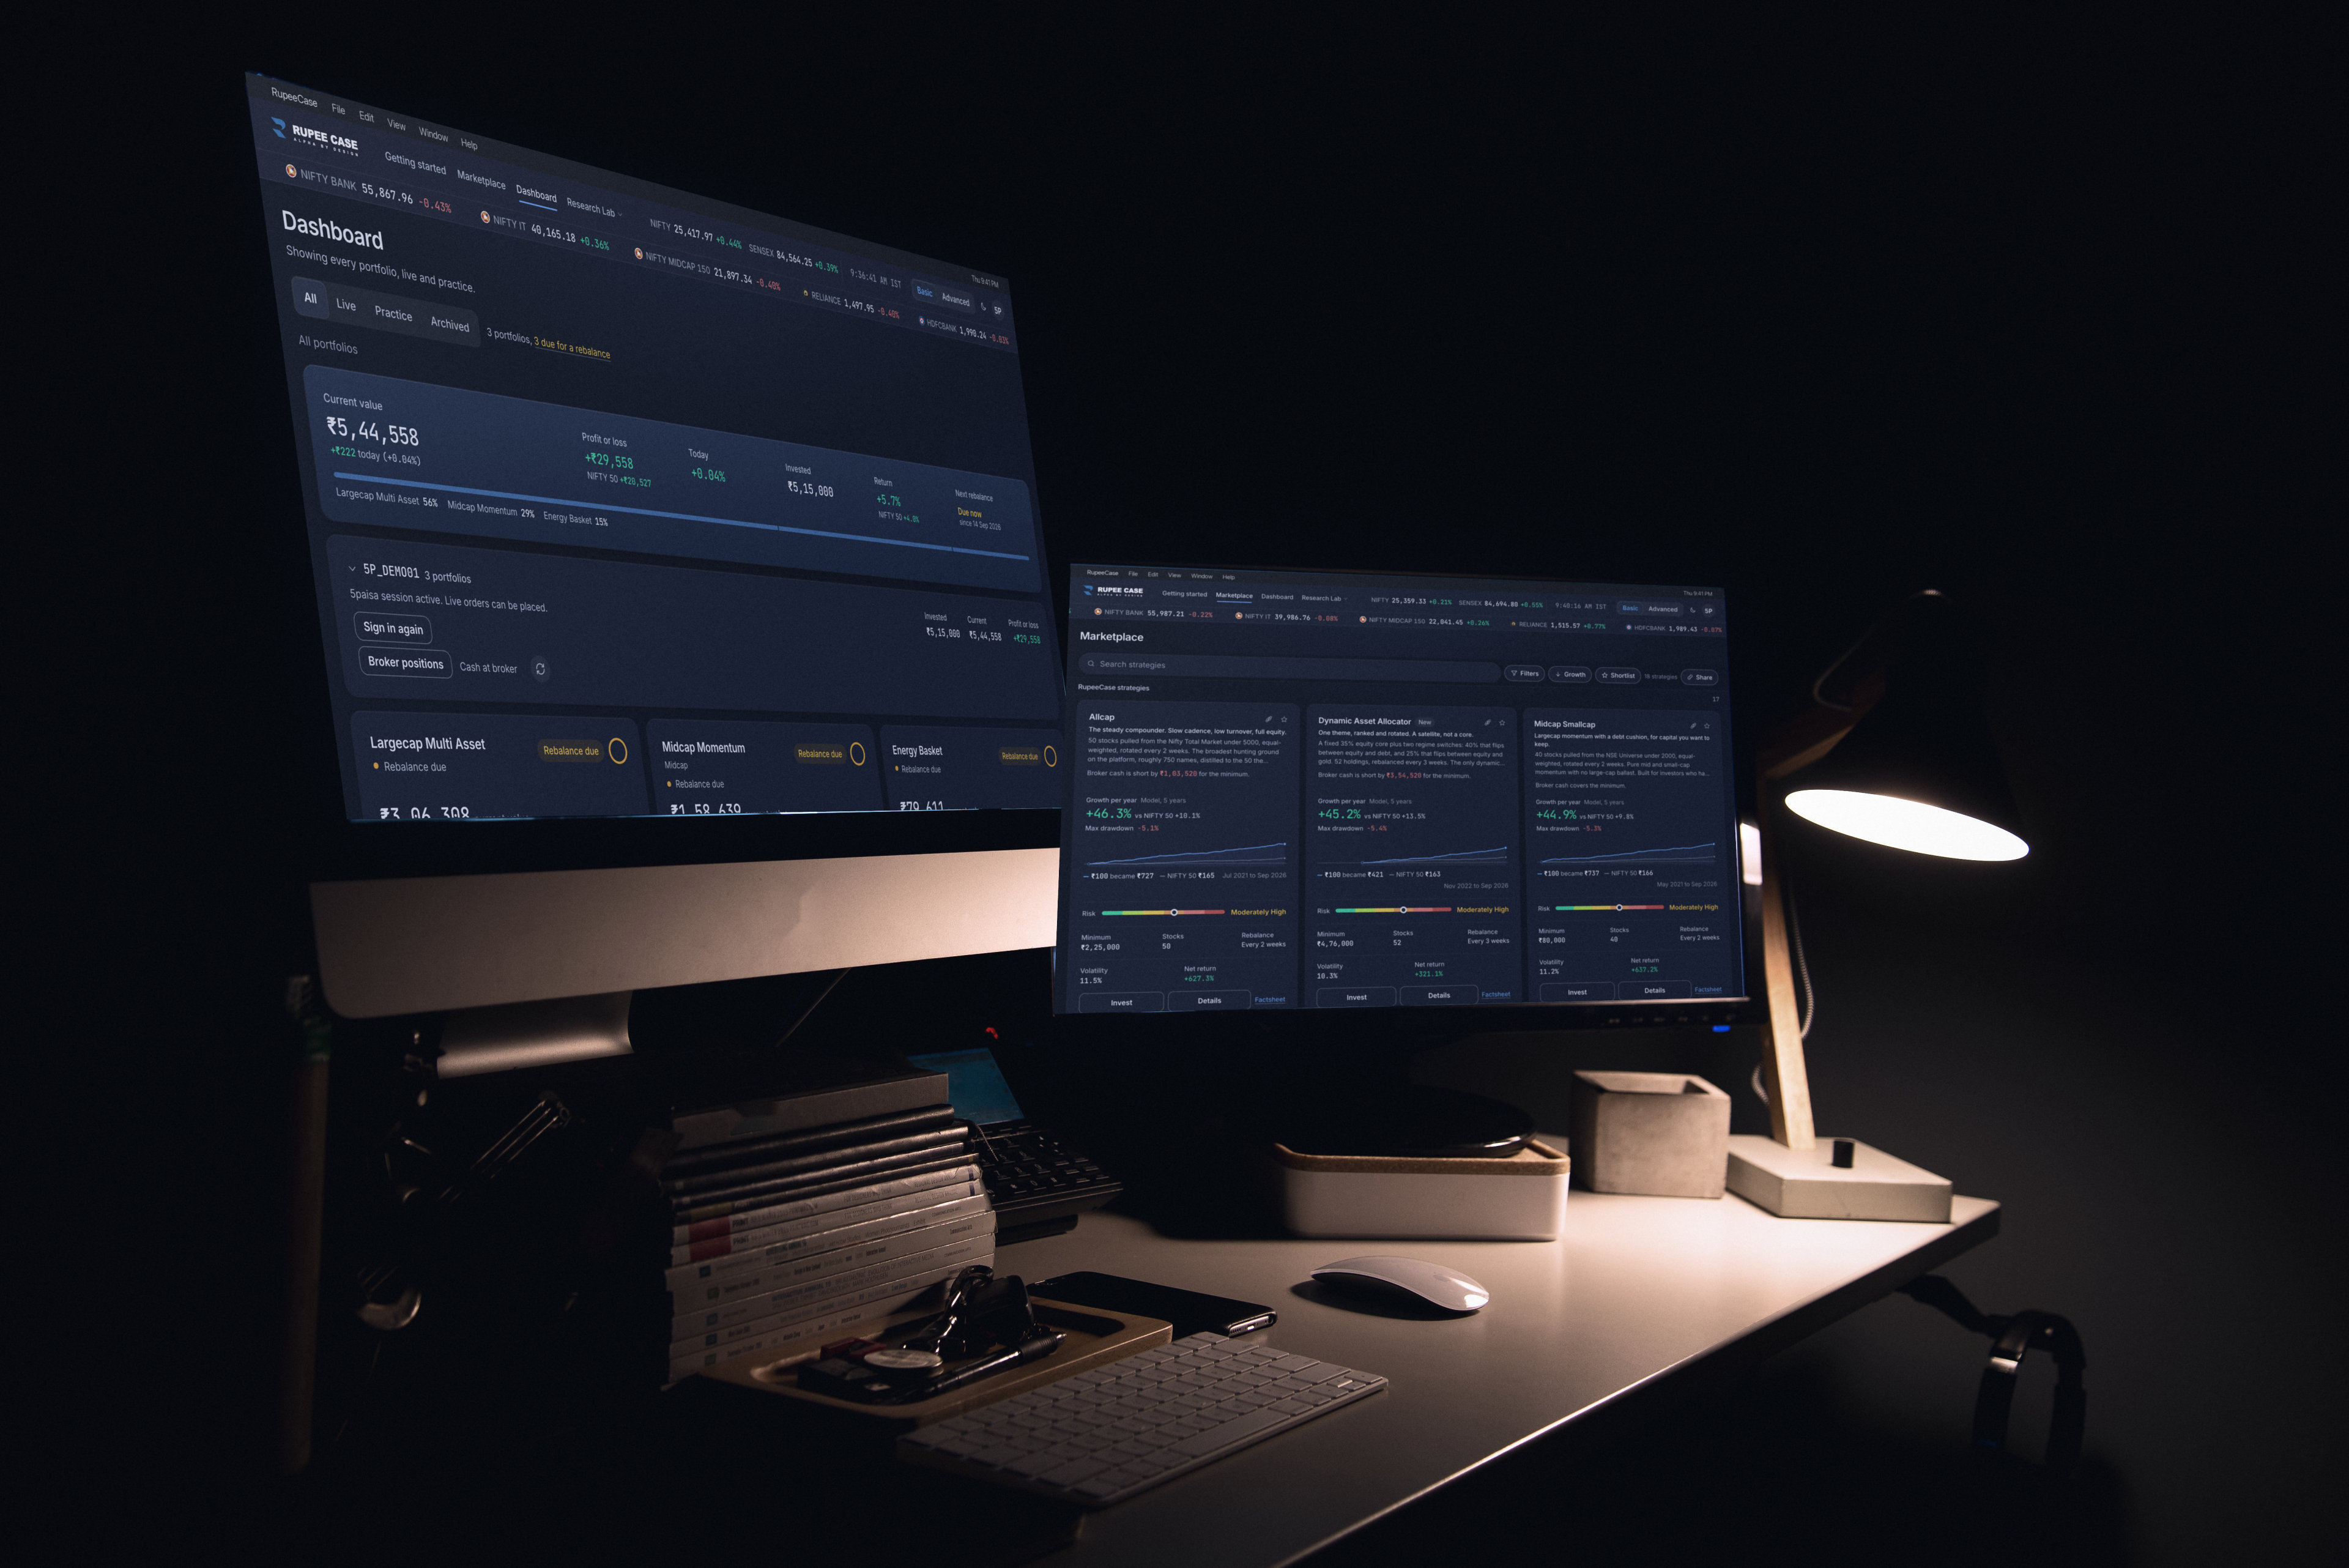
Put any strategy against an index, read its rule, every past rebalance and the full model back test after costs. Then invest in your own broker account.
- Comparestrategies and indices on one chart
- Validatethe rule and the model back test, after costs
- Investin your own demat; you approve each rebalance
Recordings of the RupeeCase app on sample data. Model, back tested figures are not a promise of future returns.
04The wealth engine
A core, satellites,
and your own margin.
Combine several index algos across risk bands in one account, and keep every figure on your actual result from the day you invested.
- Combine strategies into a core and satellites; the risk profile shows which sit within your risk envelope.
- Pledge for margin at your broker and trade on your own; margin carries risk.
- Smart ledger, order tracking and analysis on the actual result, never mixed with the model history.
- F&O for hedging, coming: only as insurance for the portfolio.
05Questions
For UHNI and HNI investors, answered.
Fees, minimums, exits and tax.
Is RupeeCase an alternative to a PMS or an AIF?
For rules based Indian equity, it can be. RupeeCase runs institutional grade index algos in your own demat, for 0.2% of traded value per rebalance. It is not itself a PMS or an AIF: QC Alpha Technologies Pvt Ltd is a technology platform, and you approve each rebalance before your broker executes it.
How do the fees compare with a PMS and an AIF?
A typical PMS charges about 2% of assets a year plus 20% of profits above a hurdle; a typical Category III AIF about 2% plus around 20%. RupeeCase charges only 0.2% of traded value per rebalance: no AUM fee, no profit share, no performance fee.
What are the minimums?
SEBI sets ₹50 lakh for a PMS and ₹1 crore per investor for an AIF. RupeeCase strategies start from ₹26,000, up to ₹3,02,000 for the largest published minimum (lineup of 17 Jul 2026), because each needs enough to hold whole shares at its weights.
Is there a lock in?
No. You can sell in your own broker account any trading day and the cash settles the next day. AIFs follow their scheme terms, which can include lock ins, redemption windows or a fixed tenure; a PMS follows its agreement.
How is it taxed?
You own the shares, so each sale is taxed in your hands: STCG at 20% and LTCG at 12.5% above ₹1.25 lakh a year for listed equity. A Category III AIF is generally taxed at the fund level. Consult a tax professional.
Can I combine several strategies?
Yes. Many investors combine a core strategy with satellites across risk bands. The risk profile shows which strategies sit within your risk envelope. This is not investment advice.
Explore next
Where to go next.
- CalculatorFee calculator: funds, PMS and RupeeCaseWhat fees take out over the years, in rupees
- StrategiesAll 18 RupeeCase strategiesRules, model back tests and minimums
- VersusRupeeCase vs PMSA PMS alternative without the Rs 50 lakh door
- VersusRupeeCase vs AIFQuant indices against alternative funds
- SolutionsFor family officesTailored mandates across accounts
Own the shares.
Skip the profit share.
No ₹50 lakh door, no ₹1 crore gate, no profit share. Every rule and rebalance in the open.
For institutionsFor family officesFor retail investorsAll solutions
Typical fee levels: PMS 2% of assets plus a 20% profit share, as stated on the current RupeeCase pricing page; AIF Category III about 2% plus 20%; PMS minimum ₹50 lakh and AIF minimum ₹1 crore under SEBI rules. Every product differs; read its own documents. Fee drag figures are illustrations, not forecasts. RupeeCase is a technology platform operated by QC Alpha Technologies Pvt Ltd. It is not a mutual fund, a PMS, an AIF or a SEBI registered investment adviser. Research by QC Alpha Research Pvt Ltd, SEBI research analyst registration pending. Trades execute through your own SEBI registered broker. Investments in securities markets are subject to market risks. Nothing here is investment advice.