

Every individual taxpayer in India computes tax under one of two sets of rules: a new regime with lower slab rates and almost no deductions, and an older one with higher slabs and a long list of deductions and exemptions. For FY 2026-27 the choice sits inside the Income-tax Act, 2025, which replaced the 1961 Act from 1 Apr 2026. This is education, not advice for your money, and not a substitute for a tax professional. Every rate, limit and rule below carries its source and date, and applies to FY 2026-27 (tax year 2026-27) unless stated.
- Total incomeGross income less the deductions the chosen regime allows.
- Slab taxApplied slice by slice at that regime's rates.
- RebateWipes out tax up to ₹60,000 (new) or ₹12,500 (old).
- SurchargeAdded above ₹50 lakh, with marginal relief.
- Cess4% on the tax and surcharge.
How a tax bill is built under either regime. Sources are in each section below.
6By the end you can
- Write down the slabs, rebate, standard deduction, surcharge and cess for both regimes for FY 2026-27, with their sources.
- Say which common deductions survive in the new regime and which do not.
- Compute tax under both regimes for a salary and compare the two figures.
- Find the break even amount of deductions at which the old regime matches the new.
- State when and how the choice is made for salaried income and for business income.
- Explain what happened to Form 10-IEA for tax year 2026-27.
Two regimes and the year names
Under the 1961 Act the year of income was the "previous year" and the year of filing the "assessment year". The Income-tax Act, 2025 uses one name, the "tax year". FY 2026-27 is tax year 2026-27, and income earned from 1 Apr 2026 is taxed under the 2025 Act. Income earned up to 31 Mar 2026, FY 2025-26, is still taxed and filed under the 1961 Act as assessment year 2026-27, where the new regime was section 115BAC. The 2025 Act puts it in section 202.
Read one more paragraph, 91 words
The new regime is the default. Section 202(1) says that, unless the person exercises an option under section 202(4), tax is computed at the rates of its table, on total income worked out without most exemptions and deductions (section 202(2)). The alternative is the older set of slab rates, in Part I-B of the First Schedule to the Finance Act 2026, with the exemptions and deductions the 2025 Act carries over. The Finance Bill 2026 memorandum states that no change was proposed in either set of rates for tax year 2026-27.
The new regime: slabs for FY 2026-27
| Total income | Rate | Slab tax at the top of the band |
|---|---|---|
| Up to ₹4,00,000 | Nil | ₹0 |
| ₹4,00,001 to ₹8,00,000 | 5% | ₹20,000 |
| ₹8,00,001 to ₹12,00,000 | 10% | ₹60,000 |
| ₹12,00,001 to ₹16,00,000 | 15% | ₹1,20,000 |
| ₹16,00,001 to ₹20,00,000 | 20% | ₹2,00,000 |
| ₹20,00,001 to ₹24,00,000 | 25% | ₹3,00,000 |
| Above ₹24,00,000 | 30% | ₹3,00,000 plus 30% of the excess |
Income-tax Act, 2025, section 202(1), and the Finance Bill 2026 memorandum (Feb 2026), which records the same table for tax year 2026-27. The third column is arithmetic on the rates. Cess is extra.
The slab table applies to every age. The new regime has no separate band for senior citizens.
The old regime: slabs for FY 2026-27
| Total income | Below 60 | 60 to 79 | 80 and above |
|---|---|---|---|
| Nil up to | ₹2,50,000 | ₹3,00,000 | ₹5,00,000 |
| 5% | To ₹5,00,000 | To ₹5,00,000 | Not applicable |
| 20% | To ₹10,00,000 | To ₹10,00,000 | To ₹10,00,000 |
| 30% | Above ₹10,00,000 | Above ₹10,00,000 | Above ₹10,00,000 |
Finance Act 2026 (No. 4 of 2026, assent 30 Mar 2026), First Schedule, Part I-B, Paragraph A. The age bands apply to a resident individual who is 60 or over, or 80 or over, at any time in the tax year. Slab tax for a person below 60 is ₹12,500 at ₹5,00,000 and ₹1,12,500 at ₹10,00,000.
An example of the age bands. A resident aged 62 with total income of ₹6,00,000, after deductions, pays ₹10,000 on the 5% band (₹3,00,001 to ₹5,00,000) and ₹20,000 on the 20% band (₹5,00,001 to ₹6,00,000): ₹30,000, or ₹31,200 with cess. The ₹12,500 rebate is not available because income is above ₹5,00,000. A person below 60 with the same ₹6,00,000 would pay ₹12,500 plus ₹20,000 (₹5,00,001 to ₹6,00,000), which is ₹32,500 and ₹33,800 with cess.
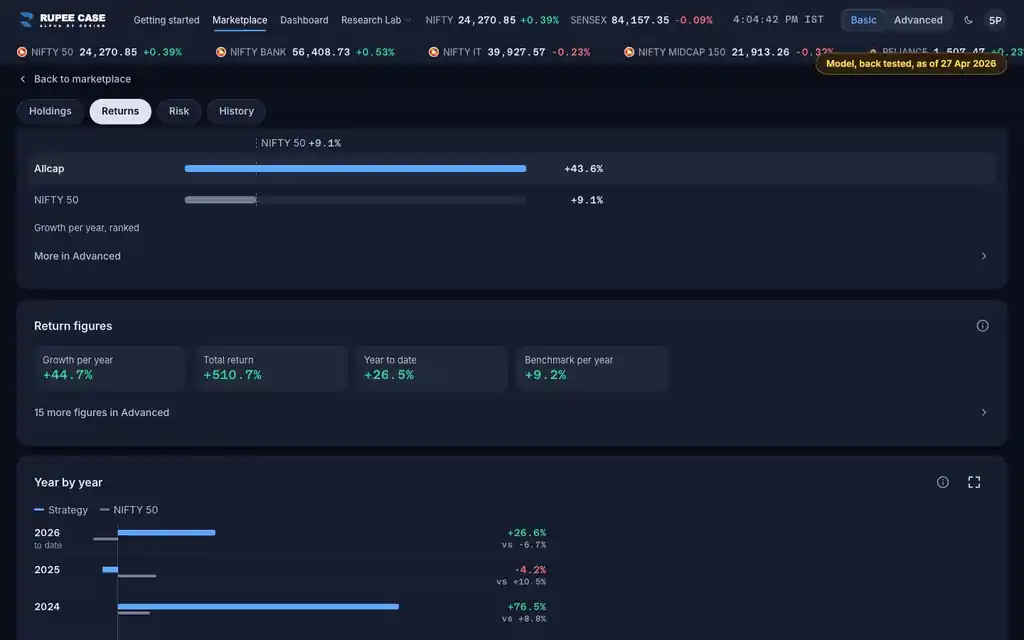
₹100 in Dynamic Asset Allocator became about ₹388 in the model
Rebate, standard deduction, surcharge and cess
Rebate. Section 156 of the 2025 Act, the successor to section 87A, gives a resident individual two rebates. Under the old regime, 100% of the tax or ₹12,500, whichever is less, if total income does not exceed ₹5,00,000 (section 156(1)). Under the new regime, if total income does not exceed ₹12,00,000, 100% of the tax or ₹60,000, whichever is less (section 156(2)(a)). The new regime rebate cannot exceed tax payable at the section 202(1) rates (section 156(3)), so it does not shield tax charged at special rates, such as capital gains (module 11.1).
| Total income | Old regime | New regime |
|---|---|---|
| Up to ₹50 lakh | Nil | Nil |
| ₹50 lakh to ₹1 crore | 10% | 10% |
| ₹1 crore to ₹2 crore | 15% | 15% |
| ₹2 crore to ₹5 crore | 25% | 25% |
| Above ₹5 crore | 37% | 25% |
Finance Act 2026, First Schedule, Part I-B, Paragraph F, and the Finance Bill 2026 memorandum (paragraph 3 of the rates for section 202): the 37% rate does not apply under the new regime. Surcharge on dividend income and capital gains under sections 196, 197 and 198 is capped at 15% in both.
Read 4 more paragraphs, 267 words
Marginal relief at ₹12 lakh. Section 156(2)(b) handles income just above the line. If total income exceeds ₹12,00,000 and the tax exceeds the excess over ₹12,00,000, the rebate equals the difference. In effect, tax cannot be more than the amount by which income exceeds ₹12,00,000. At ₹12,25,000 the slab tax is ₹60,000 plus 15% of ₹25,000, which is ₹63,750. The excess is ₹25,000, so the payable tax is ₹25,000 and with cess ₹26,000. The relief fades where slab tax and excess meet, at about ₹12,70,588.
Standard deduction. Section 19(1) of the 2025 Act, Table Sl. No. 2, gives ₹75,000 or the salary, whichever is less, where tax is computed under section 202(1), and ₹50,000 or the salary, whichever is less, in any other case. Together with the rebate, a salaried person with no other income and no other deduction pays no tax in the new regime up to ₹12,75,000 of salary: ₹12,75,000 less ₹75,000 is ₹12,00,000.
Surcharge and cess. The Finance Act 2026 and the Finance Bill memorandum fix the surcharge on income tax for individuals by total income. Health and Education Cess is 4% on the tax including surcharge, with no marginal relief on the cess.
Marginal relief applies at each surcharge threshold. Take a new regime total income of ₹51,00,000. Slab tax is ₹11,10,000 (₹3,00,000 to ₹24 lakh plus 30% of ₹27,00,000). The surcharge of 10% would add ₹1,11,000 for ₹12,21,000. But tax at ₹50,00,000 is ₹10,80,000, so tax plus surcharge cannot exceed ₹10,80,000 plus the ₹1,00,000 by which income crosses the line, which is ₹11,80,000. Cess of 4% brings the payable amount to ₹12,27,200.
Which deductions survive in the new regime
Section 202(2)(a) lists what the new regime strips out. Among other items, it bars certain exemptions in Schedule III, the deduction for professional tax, the house property interest deduction on a self-occupied home, and Chapter VIII deductions other than sections 124(1), 124(2), 125(2) and 146. It also bars set off of a house property loss against other income. The standard deduction at the higher ₹75,000 stays.
| Item | Old regime | New regime |
|---|---|---|
| Standard deduction | ₹50,000 | ₹75,000 |
| Section 123: EPF employee share, PPF, tuition fees, life premia and more | Up to ₹1,50,000 | No |
| Health insurance, section 126 | ₹25,000 for self and family, ₹25,000 for parents; ₹50,000 for each if a senior citizen | No |
| NPS, employee, section 124(3) | Further ₹50,000 | No |
| NPS, employer, section 124(1) and (2) | 10% of salary, 14% for a Government employer | 14% of salary |
| House rent allowance (Schedule III, Sl. No. 11; Rule 279) | Least of three limits | No |
| Interest on a home loan, self-occupied, section 22(2) | Up to ₹2,00,000 | No |
| Leave travel concession (Schedule III, Sl. No. 8) | Yes | No |
| Professional tax, section 19(1) | Yes | No |
Income-tax Act, 2025, sections 19, 22, 123, 124, 126 and 202(2), and Schedule III; Income-tax Rules, 2026, Rule 279. Under Rule 279, house rent allowance is exempt up to the least of the allowance received, rent paid less one tenth of salary, and 50% of salary in Mumbai, Kolkata, Delhi, Chennai, Hyderabad, Pune, Ahmedabad and Bengaluru, or 40% elsewhere.
Read one more paragraph, 84 words
Items that are not on the list of exclusions stay in both regimes, such as the gratuity entries of section 19, income excluded by Schedule II (which includes PPF interest and maturity), and the employer's NPS and provident fund contributions within the ₹7,50,000 aggregate cap of section 17(1)(h). Deductions for interest on a let-out property survive too, since section 202(2)(a)(v) bars only the interest deduction for a property that is self-occupied. Module 20.4 and module 20.5 follow the two schemes that matter most here.
House rent allowance in rupees
HRA is the old regime item with the most arithmetic. Rule 279 takes the least of three figures, where "salary" means basic pay plus dearness allowance if the terms of employment provide for it. Take annual salary of ₹6,00,000 in Bengaluru, HRA received of ₹3,00,000 and rent paid of ₹2,40,000.
| Limit | Working | Amount |
|---|---|---|
| HRA received | As paid | ₹3,00,000 |
| Rent less one tenth of salary | ₹2,40,000 − ₹60,000 | ₹1,80,000 |
| 50% of salary, a listed city | 50% × ₹6,00,000 | ₹3,00,000 |
| Exempt (least) | ₹1,80,000 |
Income-tax Rules, 2026, Rule 279, for Schedule III Sl. No. 11 of the Income-tax Act, 2025. The condition that the person does not own the home occupied, and has paid the rent, comes from Schedule III. The ₹1,80,000 is the HRA figure in the ₹15 lakh row below, where basic pay is taken as ₹6,00,000.
The remaining ₹1,20,000 of HRA is taxed as salary. The exemption exists only in the old regime, so the same person in the new regime pays tax on the whole ₹3,00,000.
A worked comparison at four salary levels
The figures below are for a salaried individual below 60 with no other income. The old regime column assumes the deductions listed; the new regime takes only the standard deduction. Tax includes 4% cess. Nothing here is a recommendation: each person's deductions differ, and that difference is the whole point.
- ₹9,00,000 salary. Old deductions of ₹3,25,000: standard ₹50,000, section 123 ₹1,50,000, health insurance ₹25,000, house rent allowance exempt ₹1,00,000.
- ₹15,00,000 salary. Old deductions of ₹4,55,000: standard ₹50,000, section 123 ₹1,50,000, NPS under section 124(3) ₹50,000, health insurance ₹25,000, house rent allowance ₹1,80,000.
- ₹25,00,000 salary. Old deductions of ₹6,00,000: standard ₹50,000, section 123 ₹1,50,000, NPS ₹50,000, health insurance ₹50,000 for self and parents, house rent allowance ₹3,00,000.
- ₹40,00,000 salary. Old deductions of ₹9,80,000: the ₹25 lakh list with house rent allowance ₹4,80,000, plus ₹2,00,000 of interest on a self-occupied home loan on a house in another city.
| Salary | Old deductions | Old regime tax | New regime tax |
|---|---|---|---|
| ₹9,00,000 | ₹3,25,000 | ₹28,600 | ₹0 |
| ₹15,00,000 | ₹4,55,000 | ₹1,31,040 | ₹97,500 |
| ₹25,00,000 | ₹6,00,000 | ₹3,97,800 | ₹3,19,800 |
| ₹40,00,000 | ₹9,80,000 | ₹7,47,240 | ₹7,87,800 |
Computed from the slabs, rebate, standard deductions and 4% cess above (Income-tax Act, 2025 and Finance Act 2026). At ₹9,00,000 the new regime taxable income is ₹8,25,000, slab tax ₹22,500, wiped out by the ₹60,000 rebate. At ₹15,00,000 it is ₹14,25,000 and tax ₹93,750 before cess. No surcharge applies at these levels.
- ₹9 lakh salary₹28,600
- ₹15 lakh salary₹33,540
- ₹25 lakh salary₹78,000
- ₹40 lakh salary−₹40,560
Old regime tax minus new regime tax in rupees, from the table above. A positive figure means the old regime costs more; a negative one means it costs less. Illustration, FY 2026-27.
Change the inputs in the calculator below to your own salary and deductions. It covers salaried income up to ₹50 lakh, where no surcharge applies, and leaves out other income.
The break even deduction
The useful number is not which regime is lower for a typical person but how much of deductions it takes for the old regime to catch the new one. Write the old regime deductions as D, including the ₹50,000 standard deduction. The break even D* is the amount at which tax on (salary minus D*) at old regime slabs equals new regime tax on (salary minus ₹75,000).
G = salary
D* = old regime deductions,
standard deduction included
| Salary | Break even D* | Share of salary | Deductions assumed |
|---|---|---|---|
| ₹9,00,000 | ₹4,00,000 | 44.4% | ₹3,25,000 |
| ₹15,00,000 | ₹5,93,750 | 39.6% | ₹4,55,000 |
| ₹25,00,000 | ₹8,50,000 | 34.0% | ₹6,00,000 |
| ₹40,00,000 | ₹8,50,000 | 21.3% | ₹9,80,000 |
Computed from the slabs, rebates, standard deductions and cess above. D* includes the ₹50,000 standard deduction; beyond the standard, the extra needed is ₹3,50,000, ₹5,43,750, ₹8,00,000 and ₹8,00,000.
Read 2 more paragraphs, 206 words
What a rupee of deduction is worth depends on the slab it lands in. Each ₹1,00,000 of old regime deductions saves ₹31,200 of tax with cess in the 30% slab, ₹20,800 in the 20% slab and ₹5,200 in the 5% slab, until taxable income falls to ₹5,00,000 and the section 156(1) rebate takes the rest. That is why deductions are worth more to higher earners, and why the break even stops growing once both regimes charge 30%.
The pattern is that the break even is a large share of a lower salary and a smaller share of a higher one. At ₹9,00,000 the new regime already pays nothing, so the old regime has to bring taxable income down to ₹5,00,000 to match, which takes ₹4,00,000 of deductions. From a salary of about ₹24.75 lakh, where new regime taxable income passes ₹24 lakh, both regimes charge 30% on each extra rupee, so D* settles at ₹8,50,000 and does not grow. For salaries above that, a list of qualifying deductions longer than ₹8,50,000 puts the old regime ahead in rupees that year. Whether the list is real is a matter of documents and choices already made: rent paid, a home loan, insurance premia, NPS and provident fund contributions.
How and when the choice is made
Salaried, with no business income. The choice is made year by year and can change every year. Section 202(4)(b) says the option is exercised along with the return of income, and Rule 136 of the Income-tax Rules, 2026 repeats that the option, or its withdrawal, is made in the return under section 263(1). During the year the employer deducts tax at source on salary on the basis of the claims the employee furnishes (Rule 205, Form No. 124), and the salary certificate in Form No. 130 carries a row asking whether the employee is opting out of section 202(1) (Part C, Annexure I). The return then decides the final tax and either refund or balance.
Read 3 more paragraphs, 310 words
The due date for such a return is 31 July after the tax year, so 31 Jul 2027 for tax year 2026-27, under the table in section 263(1)(c) as substituted by the Finance Act 2026. A revised return can be filed within twelve months of the end of the tax year or before assessment is complete, whichever is earlier (section 263(5)).
With income from business or profession. The rule is stricter. Under section 202(4)(a) the option must be exercised on or before the due date of the return, and once exercised it applies to later tax years too. It can be withdrawn only once, for a tax year other than the one in which it was exercised. After that withdrawal the person can never exercise the option again, unless they cease to have any business or profession income, in which case the salaried route applies. The due date is 31 Aug 2027 where accounts are not required to be audited and 31 Oct 2027 where they are. Gains from futures and options are business income (module 11.2), so a salaried person who also trades derivatives falls on this side of the line.
Form 10-IEA. For FY 2025-26 (assessment year 2026-27), under the 1961 Act, a person with business or professional income opted out of the new regime by filing Form 10-IEA on the e-filing portal. The form was notified by CBDT Notification No. 43 of 2023 dated 21 Jun 2023, and the portal's user manual says it can be filed twice in a lifetime, once to opt out and once to re-enter. For tax year 2026-27 under the 2025 Act, Rule 136 puts the option in the return itself, and I found no separate Form 10-IEA in the Income-tax Rules, 2026 for this purpose. Check the return form for the year on the e-filing portal before relying on that.
What to gather before comparing
The comparison is only as good as the list of deductions behind it. The documents that decide the old regime column are these:
- Rent receipts and the landlord's PAN for the HRA exemption. Rule 205 of the Income-tax Rules, 2026 and Form No. 124 ask for the landlord's name, address and PAN where yearly rent exceeds ₹1,00,000.
- The lender's interest certificate for a home loan. Section 22(4) requires a certificate showing the interest payable on the capital borrowed, for the ₹2,00,000 cap, and Form No. 124 asks for the lender's name, address and PAN.
- Premium receipts for health insurance under section 126, noting the senior citizen limit of ₹50,000 for each person.
- The EPF passbook, PPF statement and NPS statement for the section 123 and section 124(3) amounts; Form No. 124 names this "evidence of investment or expenditure".
- The salary structure to see whether an employer NPS contribution is possible, since that is the one retirement deduction the new regime keeps.
With those four or five numbers, total old regime deductions D can be set against the break even D* in the table above.
Two things that trip people
The default. A person who does nothing is on the new regime. If last year's return opted out, this year's must say so again unless the person is in the business route, where the option carries forward. A person with business income who has already withdrawn once cannot opt out again.
Read one more paragraph, 81 words
The deduction is for the year, not the rupee. Section 123 and the old regime reward money that went into the listed items during the tax year. They do not reward money already saved. A person who puts nothing into those items in a year has nothing to deduct, and the old regime then costs more at most salaries in the table. The choice is therefore easier to make in April, when contributions can still change, than in the following July.
Common mistakes
- Comparing tax at one salary and generalising. The old regime was dearer at three of the four salaries above and cheaper at one. The break even depends on the deductions, not the salary alone.
- Counting the standard deduction twice. It is ₹50,000 in the old regime and ₹75,000 in the new, and break even D* includes it.
- Forgetting the ₹12 lakh line. New regime tax is nil up to total income of ₹12,00,000 and ₹25,000 at ₹12,25,000. A rupee over the line costs a rupee only until about ₹12,70,588.
- Assuming business income can switch every year. Section 202(4)(a) allows one withdrawal.
- Using a surcharge table from the 1961 Act. The 37% top rate is not in the new regime.
Key takeaways
- New regime slabs for FY 2026-27 run from nil to ₹4,00,000 up to 30% above ₹24,00,000 (section 202(1)); the old regime keeps ₹2,50,000, ₹5,00,000 and ₹10,00,000 as break points (Finance Act 2026, Part I-B).
- The new regime rebate is up to ₹60,000 for income up to ₹12,00,000, with marginal relief above; the old regime rebate is ₹12,500 up to ₹5,00,000 (section 156).
- The standard deduction is ₹75,000 in the new regime and ₹50,000 in the old (section 19). A salary of ₹12,75,000 pays no tax in the new regime.
- Surcharge starts above ₹50 lakh at 10%; the new regime tops out at 25%, the old at 37%. Cess is 4% on top.
- Section 123, health insurance, the employee's NPS deduction, house rent allowance and home loan interest on a self-occupied home do not survive in the new regime; the employer's NPS contribution up to 14% does.
- At ₹9, ₹15 and ₹25 lakh the old regime cost ₹28,600, ₹33,540 and ₹78,000 more with the deductions assumed; at ₹40 lakh it cost ₹40,560 less.
- Break even deductions were ₹4,00,000, ₹5,93,750, ₹8,50,000 and ₹8,50,000 at those four salaries.
- Salaried people choose with each return; business income gets one withdrawal. For tax year 2026-27 the option sits in the return under Rule 136.
Questions readers ask
Is income up to ₹12 lakh tax free in the new regime?
Up to ₹12,00,000 of total income, yes, because the section 156(2) rebate of up to ₹60,000 covers the slab tax. A salaried person gets there at ₹12,75,000 after the ₹75,000 standard deduction. Tax charged at special rates, such as capital gains, is outside the rebate.
Can I switch regimes every year?
With no business or professional income, yes. The option is made with each return under section 202(4)(b). With such income, section 202(4)(a) lets the option be withdrawn only once.
Do I still file Form 10-IEA?
For FY 2025-26 under the 1961 Act, a person with business income used it. For tax year 2026-27, Rule 136 of the Income-tax Rules, 2026 puts the option in the return. Check the return form on the e-filing portal.
Rules and figures in this module were last verified on 31 Oct 2026. Tax and regulatory rules change; check the source before acting.